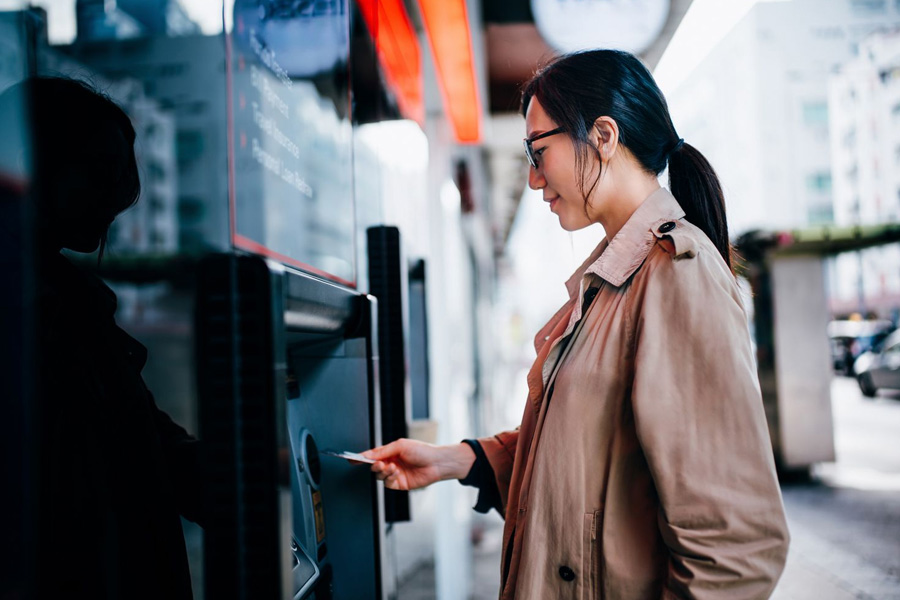
ATM fees are one of the most persistent and avoidable costs in consumer banking, and the gap between what different checking accounts charge for cash access has widened as online banks have used fee elimination as a primary competitive differentiator. The promise of no ATM fees is common enough in banking marketing that it has become almost background noise, but the specific terms behind that promise vary enough that two accounts with identical marketing language can deliver very different real-world costs depending on how you actually use cash.
Here is what separates the accounts that genuinely eliminate ATM fee costs from those that use the language without the substance.
The Difference Between No Fee ATMs and ATM Fee Reimbursement
The two primary mechanisms through which checking accounts deliver no-cost ATM access are fundamentally different in how they work and who they work for. No-fee ATM networks provide free access at specific ATMs that participate in the network, typically requiring you to find and use a network ATM rather than any ATM that is convenient. ATM fee reimbursement accounts allow you to use any ATM and reimburse the fees charged by the ATM operator after the fact.
No-fee network access is most valuable when the network is large enough and distributed enough that finding a network ATM in your area is consistently practical. A network with fifty thousand ATMs nationally provides meaningfully better coverage than one with five thousand, and the geographic distribution of those ATMs within the specific areas you frequent determines how often network access is practical versus inconvenient.
Fee reimbursement is most valuable when your cash usage takes you to locations where network ATMs are not available, when you travel frequently, or when the convenience of using any ATM without planning matters more than the mechanics of finding a specific network location. Understanding which mechanism a specific account uses and how well it matches your actual cash access patterns is the first step in evaluating whether the no-fee promise delivers real value for your situation.
Checking Accounts With No ATM Fees for Withdrawal Worth Considering
The accounts that consistently deliver the most complete elimination of ATM fee costs combine broad network access with reimbursement for out-of-network fees, providing coverage that works regardless of where you need cash rather than only in locations where network ATMs are conveniently located.
SoFi’s checking accounts with no atm fees provide members with access to a network of ATMs with no fee charged by SoFi, alongside the broader banking features that make the account useful as a primary checking relationship rather than a specialized account opened specifically for ATM access. The combination of no monthly fees, competitive interest rates on checking balances, early direct deposit, and ATM fee coverage makes it one of the more complete checking account propositions currently available for customers whose banking needs extend beyond just cash access.
Other accounts consistently cited for strong ATM fee elimination include Schwab Bank’s High Yield Investor Checking, which reimburses all ATM fees worldwide without a monthly cap and has no minimum balance requirement; Chime, which provides access to a large network of fee-free ATMs; and Ally Bank, which reimburses up to ten dollars per month in out-of-network ATM fees alongside competitive interest on checking balances.
Reimbursement Caps That Limit the Actual Coverage Provided
ATM fee reimbursement accounts frequently advertise the feature without prominently disclosing the monthly cap that limits how much reimbursement is actually provided. An account that reimburses ATM fees up to ten dollars per month is not providing unlimited ATM fee coverage. For a customer who makes multiple ATM withdrawals per month at ATMs that charge three to four dollars per transaction, a ten-dollar monthly cap is exhausted in three transactions and provides no reimbursement for subsequent withdrawals in the same month.
Comparing the reimbursement cap against your actual ATM usage pattern rather than the advertised feature tells you whether the reimbursement provides meaningful coverage or whether you will routinely exceed the cap and pay fees beyond it. Accounts with no reimbursement cap, or with caps that significantly exceed your typical monthly ATM fee exposure, deliver the no-fee promise more completely than those with low caps that apply in practice only to infrequent cash users.
The Size and Distribution of In-Network ATM Access
For accounts that provide no-fee access through a specific ATM network rather than through reimbursement, the size and geographic distribution of that network determines how often the no-fee promise is practically accessible. Network size claims measured in total ATM count can be misleading if those ATMs are concentrated in specific geographic areas or affiliated with specific retail chains that are not present in your area.
Checking the specific ATM locator tool for any account you are considering before opening it gives you a realistic picture of how many fee-free ATMs are accessible in the areas where you actually use cash, rather than relying on a national total that may not reflect local availability. An account with forty thousand network ATMs in urban areas may provide fewer practical options in your specific location than a smaller network that is better distributed across the areas where you live, work, and travel.
Whether the No-Fee Promise Extends to International ATM Use
For customers who travel internationally, the ATM fee structure during international travel is as important as the domestic coverage. International ATM fees typically involve two separate charges: the fee charged by the foreign ATM operator and a foreign transaction fee charged by the home bank for currency conversion. Accounts that eliminate domestic ATM fees but charge significant foreign transaction fees and do not reimburse international ATM operator fees are not delivering comprehensive fee elimination for traveling customers.
Accounts that provide both international ATM fee reimbursement and zero foreign transaction fees deliver the most complete ATM fee elimination for customers who travel internationally with any regularity. The Schwab Bank High Yield Investor Checking account has become a reference standard for international ATM fee elimination specifically because it reimburses ATM fees worldwide without a cap and charges no foreign transaction fees, making it a particularly strong option for frequent international travelers regardless of its other features.
Interest Rates on Checking Balances That Add Value Beyond Fee Elimination
A checking account that eliminates ATM fees while paying no interest on the balance it holds is delivering one benefit while missing another that the best online checking accounts provide simultaneously. The interest rate on checking balances has historically been near zero at most institutions, but online banks that pay meaningful rates on checking account balances alongside competitive savings rates change the financial calculation of where to hold transaction funds.
Checking accounts that pay interest rates above the national average on all balances without a minimum threshold requirement deliver ongoing financial value that fee elimination alone does not. For customers who maintain meaningful balances in their checking account between paydays, the interest earned on that balance over the course of a year represents a real return that compounds the value of choosing an account with competitive rates over one that simply eliminates fees.
No Monthly Maintenance Fees That Would Offset the ATM Fee Savings
An account that eliminates ATM fees but charges a monthly maintenance fee is not delivering net fee elimination for customers who pay that monthly charge. A ten dollar monthly fee that cannot be waived costs one hundred twenty dollars annually, which exceeds the ATM fee savings for any customer who does not make enough ATM withdrawals to generate that level of fee exposure through standard per-transaction ATM fees.
The best no-ATM-fee checking accounts combine ATM fee elimination with no monthly maintenance fees, creating a checking relationship that costs nothing in ongoing fees regardless of account balance or activity level. Accounts that waive monthly fees only when minimum balance or direct deposit conditions are met are delivering conditional fee elimination rather than genuine fee-free banking, and the conditions that must be maintained to avoid fees are worth understanding before choosing the account.
The Mobile Banking Experience That Makes the Account Practical
ATM fee elimination is a meaningful financial benefit, but it is one feature within a checking account relationship whose overall utility depends on the quality of the mobile banking experience that surrounds it. An account with excellent ATM coverage whose mobile application is unreliable, difficult to navigate, or missing features that make everyday banking management practical is delivering one strong feature within a mediocre overall experience.
The mobile banking features that make a checking account genuinely useful include real-time balance and transaction visibility, mobile check deposit with rapid fund availability, easy bill payment and person-to-person transfer capabilities, ATM locator functionality that helps you find fee-free ATMs before you need cash, and push notifications that keep you informed of account activity including ATM transactions. Accounts that deliver these features alongside ATM fee elimination provide a checking relationship that works well for all the ways you manage money, not only for cash access.
Overdraft Policies That Protect You Without Generating Fee Revenue
The checking account relationship extends beyond normal balance management to how the account handles situations where a transaction would overdraw the account. Overdraft fees are one of the most significant sources of banking revenue generated from customers in the moments when they are most financially vulnerable, and the overdraft policy of a checking account matters as much as its ATM fee structure for customers who occasionally manage tight account balances.
Accounts that offer no-fee overdraft protection up to a defined limit, that provide real-time balance notifications that help customers avoid overdrafts before they occur, or that decline transactions rather than allowing them to overdraw the account and generate fees all handle overdraft situations in ways that prioritize customer financial health over fee generation. Understanding the overdraft policy of any account you are considering alongside its ATM fee structure gives you a complete picture of the account’s fee posture rather than an incomplete one focused on the most advertised feature.
Customer Service Accessibility When ATM Issues Arise
ATM transactions occasionally go wrong in ways that require customer service intervention: disputed charges, failed withdrawals where the ATM did not dispense funds but the account was debited, or reimbursement claims that did not process as expected. The quality and accessibility of customer service when these issues arise determines how quickly they are resolved and how much frustration the resolution process involves.
Online banks without branch networks need to resolve ATM-related issues entirely through digital and phone support, and the responsiveness of that support at the times when ATM issues most commonly occur, which is not always during standard business hours, determines the practical experience when something goes wrong. Banks with in-app chat support accessible without a separate login, reasonable phone wait times, and representatives who can resolve common ATM disputes without requiring multiple contacts or escalations handle these situations in ways that maintain customer confidence rather than eroding it.